Slip & Fall
What Is the Average Slip-and-Fall Settlement in New York? A Bronx Case-Value Guide
Start with the number a Bronx fall victim is searching for
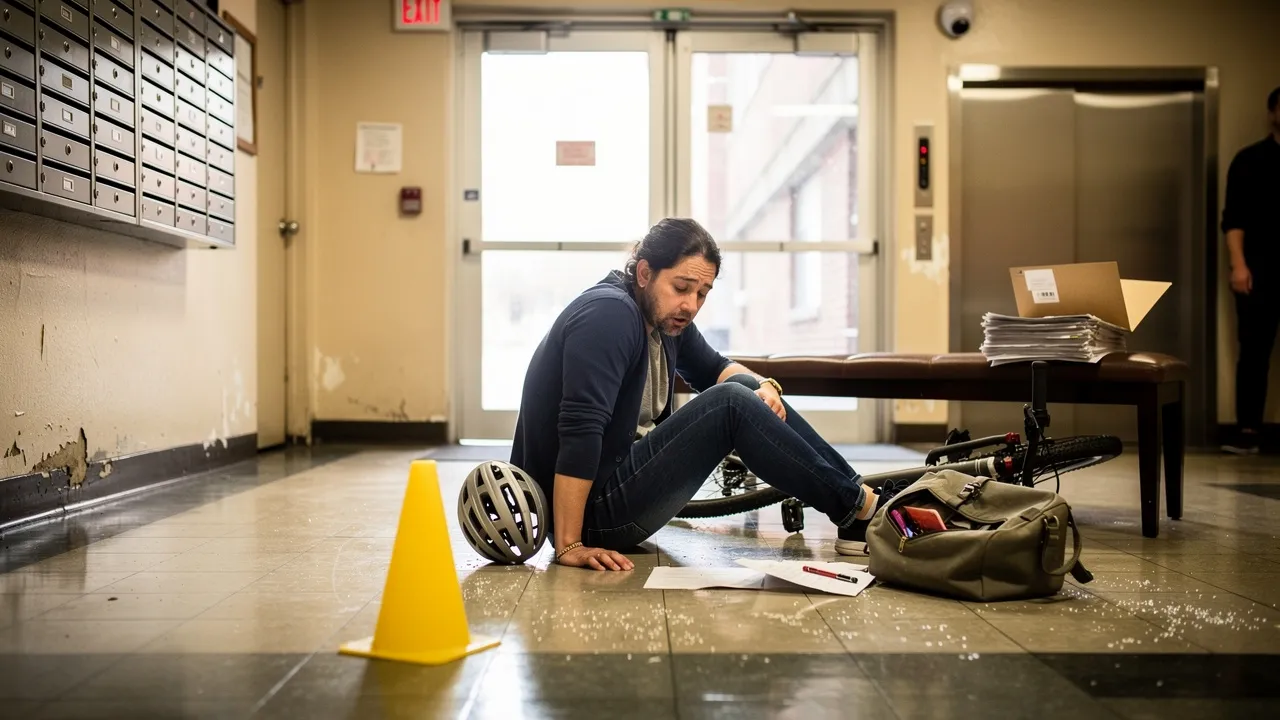
You are standing in a Bronx apartment lobby after slipping on a wet floor, with pain setting in and no clear idea what your claim might be worth. This guide will help you treat settlement figures as comparison points, then test them against your injury, proof of the hazard, losses, fault, and available coverage.
There is no single number that can value every New York slip-and-fall claim. Those figures describe selected groups, not a promise about your claim.
Start with the question behind the number: what does your own record show? A useful review asks what injury was diagnosed, how treatment developed, what income and expenses were lost, what evidence connects the property condition to the fall, how fault may be assessed, and whether available insurance could cover the damages. A headline figure becomes useful only after those questions are separated and examined.
The sections below move from published comparisons to the facts that can change the result. Keep the categories distinct. A settlement statistic, a jury verdict, gross damages, and the amount ultimately recovered are not interchangeable.
Treat published settlement ranges as context, not a personal valuation
Undated published figures can serve only as illustrative comparisons; a range is meaningful when you know what cases it measures. One undated report gives $134,656 as the median for cases meeting New York’s “serious injury” threshold and an average of $2.1 million for catastrophic injuries; treat these figures as illustrative comparisons, not a current average or a prediction.
Those numbers should not be blended into one average. They use categories with different injury descriptions and measure a median for one group and an average for another. Because no sample, methodology, or date is stated for these figures, treat them as undated illustrations rather than current, directly comparable settlement data. Neither figure tells you where your claim belongs without a closer look at diagnosis, treatment, permanence, losses, liability evidence, and coverage.
Before comparing a published figure with your circumstances, write down four details:
- Population: What types of injuries and claims does the number include?
- Measure: Is it a median, an average, a range, a settlement amount, or a verdict amount?
- Geography: Does it concern New York generally, New York City, or a different local market?
- Timeframe: When were the cases resolved or when was the analysis prepared?
An undated report compares $265,000 in Manhattan with $180,000 in Syracuse for the same injury; treat those amounts as an illustrative comparison, not a current Bronx valuation. That comparison may show why location matters in the report’s sample, but it is not a Bronx valuation and should not be carried over to your case as a fixed adjustment.
Use the figures to ask better questions, not to predict an amount. If your injury, property setting, evidence, or losses differ from the group being measured, the comparison becomes weaker.
Separate settlement data from verdicts and unlike comparisons
Settlement data and trial verdict data answer different questions. A settlement figure reflects an agreement between the parties. A verdict figure reflects an award in a trial. Treating both as entries in one universal average can make the comparison look more precise than it is.
A cited New York trial matter states that a jury awarded $1,300,000 on July 21, 2023, for past and future pain and suffering and future medical expenses. That is a dated award in one trial matter. It is not a typical settlement amount and does not predict what another fall claim will produce.
A separate cited source reports a $287,628 median compensatory damages award for New York personal-injury trials, compared with a national median of $34,550. That number measures trial awards, not slip-and-fall settlements in the Bronx. It can provide background about the source’s selected trial population, but it cannot be used as your case value.
Keep these labels beside every figure you save:
- Settlement: an amount agreed before a final trial result.
- Verdict or award: an amount determined in a trial matter.
- Median: a midpoint reported for a defined group, not a standard payment.
- Average: a calculation that can be affected by unusually high or low results.
Also separate unlike injuries. A trial involving future medical expenses is not a clean comparison to a short treatment course. A catastrophic injury is not a clean comparison to a sprain. Once you label the measure, date, injury group, geography, and outcome type, you can see what a figure can show and where it stops.
Begin the valuation screen with injury severity and treatment
Your injury record is the first practical screen because the fact that you fell does not describe the resulting harm. Record the diagnosis, the body parts affected, the treatment received, any procedure, the restrictions imposed, and the effect on ordinary activities. Do not reduce the assessment to whether surgery occurred.
A published analysis says sprains, bruises, and soft-tissue injuries may yield lower compensation, while fractures, spinal damage, or head trauma significantly increase settlement value. The same source does not turn those categories into automatic amounts; it shows why the medical description must be specific.
Treatment can add another important comparison point. A published analysis states that cases requiring surgery average 3.2 times the value of non-surgical injuries of the same type. That is a reported relationship within the analysis, not a multiplier to apply to your own claim. Your records still need to show what happened, why treatment was provided, and what limitations remain.
Organize the injury screen around these questions:
- What diagnosis appears in the medical records?
- What treatment has already occurred, and what treatment remains planned?
- Did the injury affect walking, lifting, sleeping, working, or other ordinary activities?
- Are there documented restrictions, disability, disfigurement, or continuing symptoms?
- Are the records consistent about the injury, the fall, and the treatment timeline?
The comparison becomes more useful when you can distinguish a temporary complaint from a fracture, spinal injury, head trauma, or condition involving lasting limitations. It also becomes more honest when you keep uncertainty visible. Do not choose a published category merely because it carries a larger figure; match the category to the records you actually have.

Build the damages record behind the headline amount
A settlement discussion needs more than an injury label. Build a damages record that shows the financial losses and the effect the injury has had on your life. Economic damages include medical bills, lost wages, and costs of medical equipment. Non-economic damages compensate for pain and suffering, emotional distress, disability, disfigurement, and loss of enjoyment of life.
Keep the two categories separate while you gather information:
- Medical losses: bills, treatment statements, equipment costs, and related expenses.
- Income losses: missed work, reduced earnings, and employment records showing the effect of the injury.
- Life impact: pain, emotional effects, disability, disfigurement, and activities you could no longer enjoy in the same way.
- Future needs: records or professional recommendations describing continuing treatment or limitations, when those records exist.
A cited source says medical expenses are typically the largest component of economic damages in slip-and-fall cases and that thorough treatment documentation is crucial for maximizing recovery. Preserve every treatment record and bill in date order, including records that show follow-up care rather than only the first visit.
Lost income also needs detail. Save pay records, employer communications, schedules, leave documentation, and a simple timeline of days or duties affected. Those records do not decide the claim by themselves, but they help distinguish a general statement that you missed work from a documented loss.
Do not treat pain and suffering as a substitute for medical proof. The medical record explains the injury and treatment; your own notes can describe pain, sleep disruption, mobility limits, and changes in daily activities. Keep those notes factual and dated. Together, the records let you compare your damages with a published figure without pretending that a broad category captures your particular losses.
Test the property and liability evidence before weighing value
Injury severity and property responsibility are separate questions. A serious injury does not by itself prove that the property condition created legal responsibility, and a strong liability record does not tell you how severe the injury will become. Examine both tracks before relying on a settlement comparison.
Property type can affect the figures reported in an analysis. One published analysis states that construction-site cases can reach $10,000,000, while most retail and restaurant falls resolve well below $300,000. Those are broad reported comparisons, not a promise for a construction, restaurant, retail, apartment, or sidewalk fall in the Bronx. Use the property setting to identify which evidence matters, not to select a number automatically.
For constructive notice, a New York decision states that a defect must be visible and apparent and must exist long enough before the accident for employees to discover and remedy it. The timing and visibility of the condition therefore matter. A fall report that says only “I slipped” may not answer what the condition was, how long it existed, or who could have addressed it.
The same decision involved paper that could have been placed on the ground only minutes or seconds before the accident; the decision said that concluding otherwise would have been speculation. That example shows why you should not assume that a condition was present long enough for notice without supporting facts.
Build the liability side of your file with:
- Photos or video showing the condition, surrounding area, lighting, and scale, if available.
- The precise location and property type.
- Your account of when you first noticed the condition and what happened next.
- Names and contact information for witnesses.
- Any report or communication made to a property representative.
- Clothing, footwear, or other physical items that may help preserve the event’s details.
The aim is not to label the property owner responsible before the facts are reviewed. The aim is to preserve the facts that bear on the condition, visibility, timing, notice, and connection between the property and your fall.

Account for comparative fault and the available coverage
A case can have documented injuries and still require a separate review of fault and insurance. A cited New York explanation states that compensation is reduced by a claimant’s percentage of fault: when damages total $100,000 and the claimant is 20 percent at fault, the recovery in that example is $80,000. Treat that as an illustration of the calculation described in the source, not as a formula that determines your own percentage.
Your evidence should therefore address what you saw, where you were walking, the condition of the area, lighting or obstructions, warnings, and what each available account says about the event. Do not guess at a percentage before the facts and records have been reviewed.
Insurance creates another boundary. Insurance settlements are typically limited to the property owner’s policy limits, which may not cover all damages. For minor injuries, a settlement may cover expenses and inconvenience; for severe injuries involving long-term medical needs or reduced quality of life, it may not be enough.
Separate these questions when you organize the coverage file:
- What property, business, landlord, or other defendant is connected to the location?
- What insurer or claim information has been provided?
- Is the available policy information complete, or is coverage still unclear?
- Do the documented medical, income, and life-impact losses appear likely to continue?
- Does the available coverage appear to address the full set of damages being documented?
A policy limit is not a measure of injury severity. It is a coverage constraint that may affect how a settlement can be resolved. Conversely, a severe injury does not establish that sufficient coverage exists. Keep the damages record and the coverage record separate, then examine how they interact.
Translate gross damages into a more realistic recovery picture
A reported settlement amount, a gross damages calculation, and your potential net recovery are different figures. Start by listing the economic and non-economic damages described in your records. Then identify reductions or repayment rights that may affect what remains after the claim is resolved.
Under CPLR 4545, a court must reduce an award for past or future medical costs or lost earnings by certain amounts covered by other sources, such as health insurance, when coverage is found with reasonable certainty. This rule concerns a court’s award and covered amounts; do not treat it as a simple deduction that applies identically to every settlement discussion.
Medicare, Medicaid, and some other payers may have repayment rights against a recovery for bills they covered, and valid liens must be resolved when finalizing a settlement. Those repayment issues can affect the amount that remains after a gross figure is discussed.
Use a four-line worksheet:
- Gross damages: medical losses, income losses, and non-economic losses documented in the claim.
- Coverage information: available policy details and any limits that may affect resolution.
- Covered-source issues: amounts that may be considered under the applicable rule.
- Repayment or lien issues: payer claims that may need to be resolved before finalizing a settlement.
Do not call a headline number your take-home recovery. A more realistic review keeps the source and purpose of every figure visible, including whether it describes damages, an offer, a settlement, a verdict, a court reduction, or an amount remaining after valid repayment obligations.
Preserve the records that make the assessment possible
Your evidence file should make the event understandable without relying on memory alone. Preserve the scene record, the injury record, and the loss record in separate sections, then keep a short timeline that connects them.
Keep copies, note when and where they were taken, and avoid editing the only version.
Use this Bronx slip-and-fall file checklist:
- Scene: photographs or video of the hazard, surrounding area, lighting, signs, and access route.
- People: witness names, contact information, and what each person observed.
- Reports: incident reports, police reports, written complaints, emails, and other communications.
- Medical records: initial evaluation, follow-up treatment, diagnoses, imaging, procedures, restrictions, and bills.
- Work records: missed days, reduced duties, pay information, and employer communications.
- Daily impact: dated notes about pain, mobility, sleep, activities, and care needs.
- Physical items: clothing, footwear, or other items connected to the fall, stored without alteration.
We investigate cases by gathering police reports, photos, witness statements, and medical records. Bringing those materials together gives the discussion a factual starting point and helps identify which important questions remain open.
Preservation is not the same as proving every part of a claim. It gives you an organized record to compare with published figures and to use when examining injury, notice, fault, losses, and coverage.
Know when unresolved claim variables call for professional review
A case-specific review becomes especially useful when the number you want depends on facts that are disputed, incomplete, or still developing. Consider organizing your file for professional review when you have a substantial or continuing injury, uncertainty about the hazard or notice, disagreement about fault, unclear coverage, or medical and income losses that require individual examination.
Do not wait for a published figure to answer questions that the figure cannot measure. A report cannot determine whether the condition was visible long enough, whether another account changes the fault analysis, whether treatment will continue, or how covered-source and repayment issues affect your potential recovery.
At The Law Offices of Evan W. Kohn, we handle slip-and-fall cases involving wet lobby floors, broken sidewalks, and dark stairways in apartment buildings. At The Law Offices of Evan W. Kohn, we serve clients in the Bronx and can arrange visits to clients at home or in the hospital. We offer free consultations for people who want to discuss an injury record, liability evidence, losses, and coverage questions.
Bring the organized file rather than relying on a single settlement number. The useful question is not whether your claim resembles a headline result in one respect; it is whether the medical, property, fault, coverage, and loss records fit together in a way that can be evaluated.
Take the organized questions to a case-specific next step
A published settlement figure can show a broad comparison, but it cannot value your Bronx or New York slip-and-fall claim on its own. Before taking the next step, gather the accident account, scene evidence, witness information, medical records, bills, employment records, and notes about your daily limitations. Keep every amount labeled as a settlement, verdict, gross damages figure, reduction, repayment obligation, or potential net recovery.
This article provides general information, not legal advice. A qualified legal professional must decide what the facts and records mean for your individual claim. Bring the unresolved questions with the organized file.
Questions to ask before relying on a slip-and-fall settlement figure
How should I compare two published New York slip-and-fall settlement figures?
First check whether each figure describes settlements or verdicts, a median or an average, the injury group, geography, and the date or timeframe. Do not combine figures from different populations into a single personal estimate. A report with unclear methodology, promotional framing, or unlike cases is only limited context.
Does the settlement amount show how much I will actually receive?
No. The settlement amount is a gross figure, not necessarily the net recovery. The final amount may be affected by documented damages, available coverage, court-related reductions, case costs, and repayment rights held by Medicare, Medicaid, or other payers. Review each reduction or repayment obligation separately before treating any figure as take-home money.
What should I have ready before asking for an individual slip-and-fall case review?
Prepare a short accident timeline, photographs or video of the condition, witness information, incident or police reports, medical records and bills, employment and income-loss records, and notes about continuing limitations. Also gather any insurer or property-owner communications. These materials help separate injury, notice, fault, losses, and coverage instead of relying on a broad settlement statistic.
Hurt like this?
We handle Slip & Fall cases in the Bronx.
Evan W. Kohn, Esq. — more than 35 years of Bronx personal-injury practice. Reading about it only goes so far; a free consultation tells you what actually applies to your case.